- Power of Attorney and Tax Information Authorizations remain active until formally revoked or replaced for the same matters and periods.
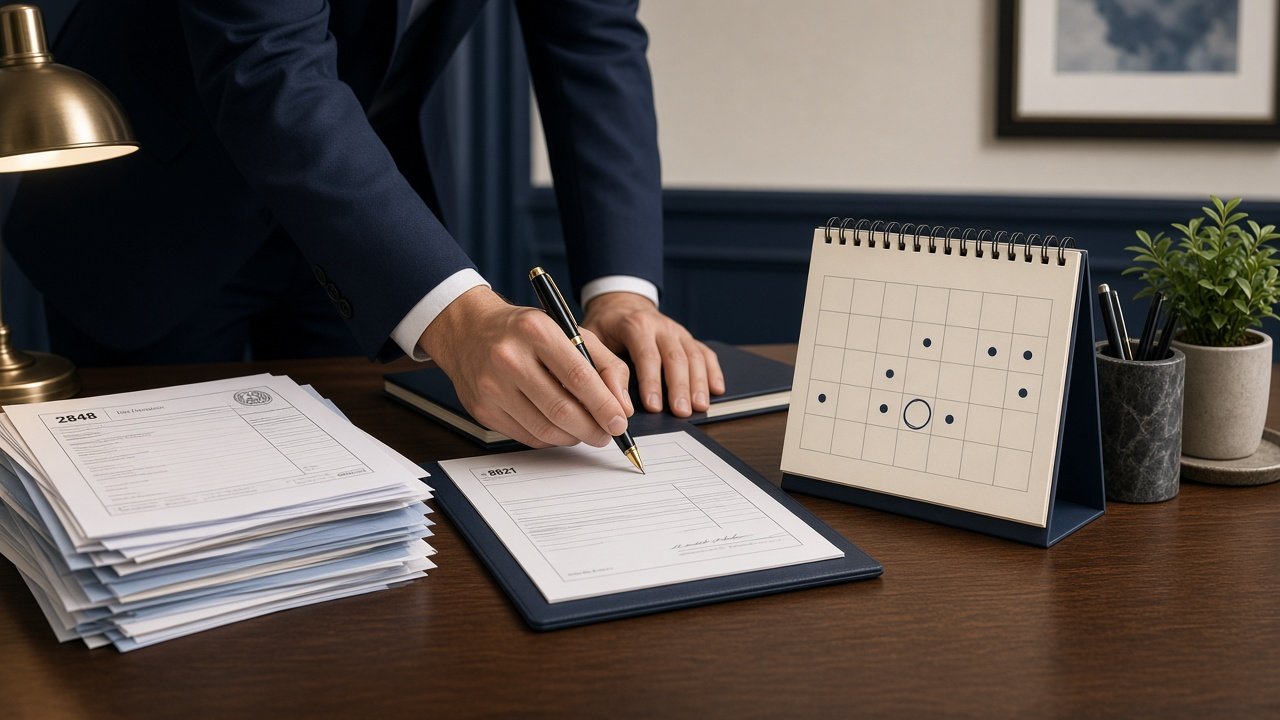
- A new Form 2848 or Form 8821 for identical tax matters and years automatically revokes the prior authorization on record.
- Oral disclosures and Third Party Designee authorizations expire automatically after the conversation or one year from the return due date.
Understanding IRS Third-Party Authorizations
The IRS allows taxpayers to grant limited access to third parties for federal tax matters. These authorizations vary by scope and purpose. Power of Attorney permits an eligible representative to advocate, negotiate and sign on your behalf. Tax Information Authorization allows a designee to receive or review confidential tax data.
Third Party Designee authority is narrower, limited to discussing a specific tax return during processing. Oral Disclosure provides one-time permission during a phone call or meeting. Each type carries distinct eligibility rules and expiration terms according to IRS guidance.
Taxpayers retain ultimate responsibility for meeting all tax obligations regardless of any authorization granted.
Power of Attorney Details and Revocation
Under IRS rules, a Power of Attorney must be executed by an individual authorized to practice before the agency, such as attorneys, CPAs, enrolled agents or certain others under limited conditions. It allows the representative to receive notices, argue facts and law, and handle specified tax years or periods.
Authorization stays in effect until revoked or withdrawn. When changing representatives for the same matters, filing a new Form 2848 automatically revokes the prior one. Alternatively, a separate revocation can be sent following the instructions on Form 2848.
Republic Tax Relief notes that individuals facing ongoing IRS tax debt questions unrelated to changing representatives may wish to contact the firm for a free, no-obligation initial consultation about private tax-resolution services and suitability for their situation.
Tax Information Authorization and Revocation Process
A Tax Information Authorization, submitted via Form 8821, lets any individual, firm or organization receive confidential information for designated tax matters and periods. It does not allow representation or advocacy. Like Power of Attorney, it is recorded on the Centralized Authorization File unless marked for specific use only.
The authorization remains valid until you revoke it or the designee withdraws. IRS instructions state that submitting a new Form 8821 covering the identical matters and years automatically revokes the earlier authorization. A written revocation may also be submitted per the Form 8821 instructions.
Oral Tax Information Authorizations can be granted during IRS calls but require explicit confirmation of identity, issues and scope.
Limited Authorizations: Third Party Designee and Oral Disclosure
Third Party Designee authority is indicated directly on a tax return and expires automatically one year after the return's due date, without extensions. It covers only processing questions, refunds, notices and math errors for that specific return.
Oral Disclosure is granted during a live IRS conversation and is limited to that single interaction unless otherwise stated. The IRS records the authorization on the taxpayer's account. Once the conversation ends, the permission is automatically revoked and cannot be used for future calls without new authorization.
For continued access beyond one conversation, the IRS recommends considering a formal Tax Information Authorization.
Practical Considerations When Switching Representatives
Taxpayers should review the exact tax matters, years and scope listed on any existing authorization before submitting a replacement. Both Power of Attorney and Tax Information Authorizations can be managed electronically through an IRS online account when submitted by an eligible professional.
Following IRS procedures precisely ensures the prior representative loses access to confidential information and representation rights for the covered periods. Low Income Taxpayer Clinics may provide independent assistance to eligible individuals.
IRS guidance checked .
General information only, not individual tax, legal, or financial advice. Rules, deadlines, and eligibility depend on your circumstances. Check current official guidance or consult a qualified professional.
Request a correction →