- The IRS notice dated September 24, 2026 seeks comments on OMB Control No. 1545-2168 for Forms 14157 and 14157-A with no changes to the collection.
- Affected parties include members of the private sector who may submit comments on the necessity, burden, and utility of the complaint process.
- Comments are due by November 23, 2026; the estimated annual burden remains 1,593 hours based on 7,500 responses at 12 minutes each.
Announcement Details and Comment Deadline
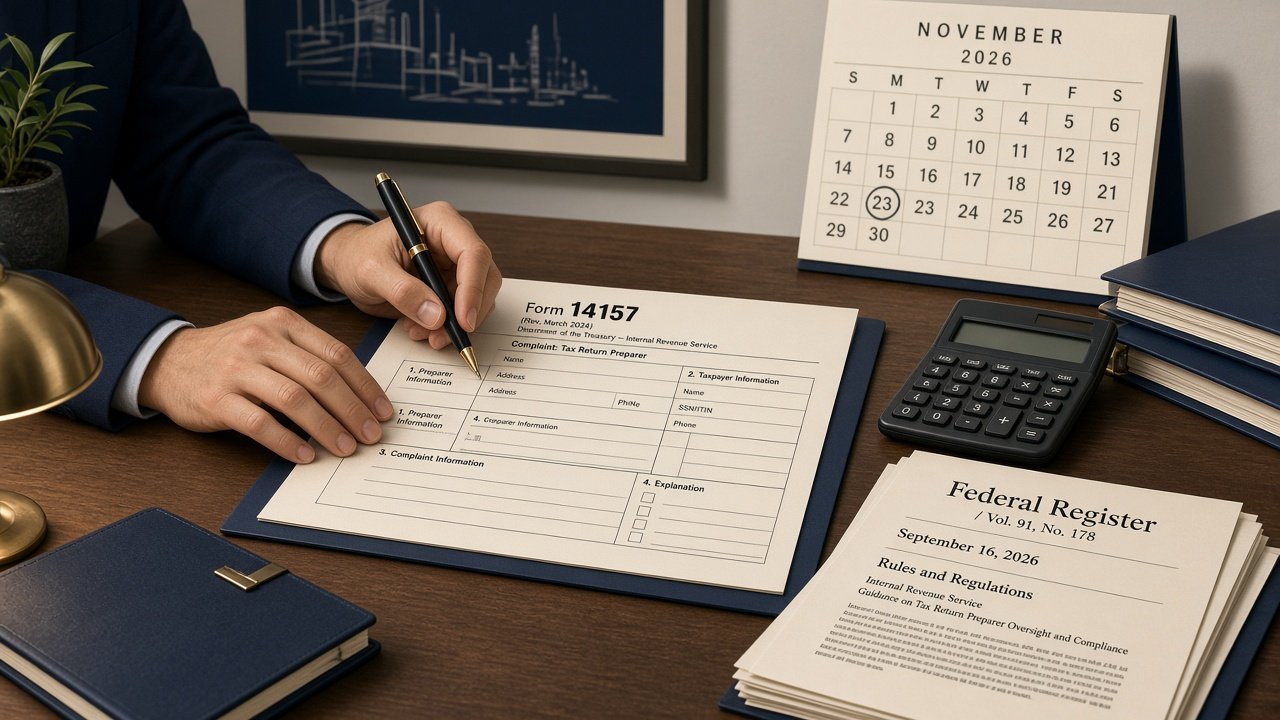
On September 24, 2026, the Internal Revenue Service issued a Federal Register notice inviting public comments on the information collection for the Tax Return Preparer Complaint Process and Fraud or Misconduct Affidavit. This is an extension of a currently approved collection under OMB Control Number 1545-2168, using Forms 14157 and 14157-A.
Written comments must be received on or before November 23, 2026 to be assured of consideration. Submissions should be directed to Andres Garcia at the IRS or via email, referencing the OMB control number.
Republic Tax Relief notes that while this process addresses complaints about tax return preparers, taxpayers facing their own existing tax-debt issues unrelated to preparer misconduct may have separate questions; the firm offers a free, no-obligation initial consultation to discuss suitability of private tax-resolution services for IRS or state tax issues.
Purpose of the Forms and Who Is Affected
Forms 14157 and 14157-A are used specifically by taxpayers to report allegations of misconduct or fraud by tax return preparers. The information collected allows the IRS to evaluate complaints and route them to the appropriate function.
The collection impacts the private sector, with an estimated 7,500 responses annually. Each response is projected to take 12 minutes, resulting in a total annual burden of 1,593 hours. There are no changes to the previously approved collection.
The notice separates the September 2026 announcement from the November 23, 2026 deadline, giving interested parties roughly two months to provide input.
How to Submit Comments and What the IRS Is Asking
Comments may address whether the information collection is necessary and has practical utility, the accuracy of the burden estimate, ways to enhance the quality and clarity of the information, methods to minimize respondent burden including automation, and estimates of associated costs.
All comments will be summarized, included in the OMB approval request, and become a matter of public record. The IRS advises against including confidential or sensitive personal information in submissions.
Requests for additional information can be directed to LaNita Van Dyke at the provided contact number. The process follows the Paperwork Reduction Act of 1995.
Background on the Information Collection
This notice continues an existing IRS mechanism designed to capture taxpayer complaints about unethical or fraudulent behavior by paid tax return preparers. The forms standardize the information needed for proper routing and review.
Readers should verify current form availability, submission methods, and any updates directly with the IRS, as the comment period focuses on potential improvements to the process rather than altering eligibility or deadlines for individual complaints.
Announcement covered: Sep 24, 2026.
General information only, not individual tax, legal, or financial advice. Rules, deadlines, and eligibility depend on your circumstances. Check current official guidance or consult a qualified professional.
Request a correction →