- The order targets excise taxes under 26 U.S.C. 4041 for diesel used by qualifying farmers and truckers from October 5 through December 31, 2026.
- Penalty relief applies to dyed diesel highway use and semimonthly deposits during the same period, but taxes are only deferred, not canceled unless Congress acts.
- Common misunderstanding: relief depends on a formal IRS determination under disaster authority and does not guarantee lower pump prices for all diesel buyers.
For background on this issue, read our Penalty relief guide.
What the Executive Order Actually Changes
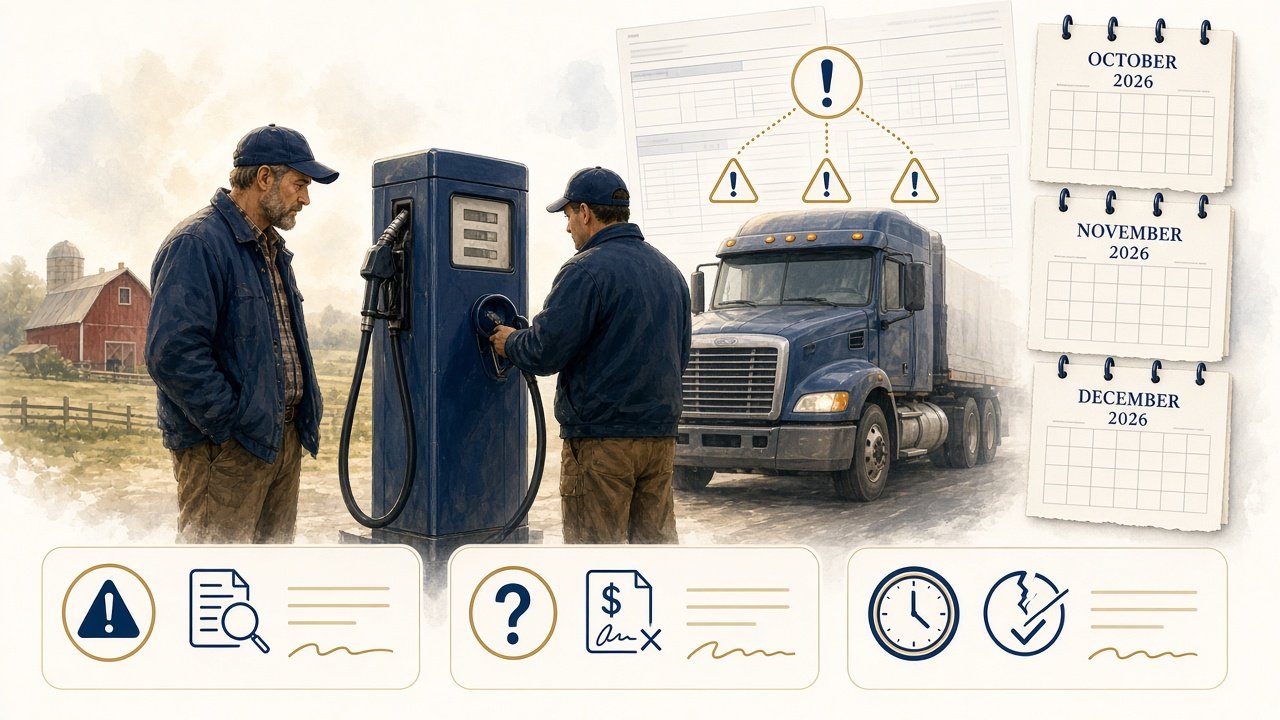
On October 5, 2026, President Trump signed Executive Order 14435 directing the Secretary of the Treasury to evaluate whether statutory authority under 26 U.S.C. 7508A allows deferral of specific federal excise taxes on diesel fuel incurred between October 5 and December 31, 2026. The affected taxes are those imposed by 26 U.S.C. 4041(a)(1)(A) and 4041(b)(1)(B).
If the Secretary determines a qualifying event has occurred and identifies affected taxpayers, payments would be postponed without penalties, interest, or additions to tax to the extent permitted by law. The order also instructs the IRS to announce it will not impose penalties under 26 U.S.C. 6715 for selling or using dyed diesel on highways during this window, and to provide relief for failure to make semimonthly deposits of the tax.
This temporary measure aims to ease cash-flow pressure on farmers and truckers facing higher diesel costs due to restricted global supply. However, the relief is not self-executing; it requires formal guidance from the Treasury and IRS that spells out covered parties, exact conditions, payment deadlines for deferred amounts, and any geographic or industry limits.
Consumer Protections and Common Misunderstandings
Many consumers assume any tax relief on diesel will automatically lower prices at every gas station. In practice, the order focuses on excise tax payment obligations for specific taxpayers rather than a broad rate cut passed directly to retail buyers. Truckers and farmers who qualify may see improved cash flow, but downstream price effects depend on market conditions and how suppliers adjust.
The order explicitly separates the deferral from any final forgiveness. Section 4 directs the Secretary only to explore avenues, including potential legislation, to eliminate the deferred tax obligation. Until such action occurs, the taxes remain due after the postponement period.
Another frequent misunderstanding involves dyed diesel rules. The announced penalty relief for highway use of dyed fuel is time-limited and does not alter the underlying legality of such use outside the relief window. The Department of Transportation is required to maintain all existing safety and compliance enforcement, so operators should not assume reduced scrutiny on fuel taxes or vehicle inspections.
Republic Tax Relief notes that while this diesel tax deferral addresses current operating costs, many farmers and trucking businesses carry separate longstanding IRS or state tax debts from prior years. Those with existing tax liabilities unrelated to this announcement can schedule a free, no-obligation initial consultation to discuss private tax-resolution options, suitability, scope, fees, and how best to communicate with the IRS.
Implementation, State Coordination, and Next Steps
The Treasury must issue guidance within days of the order that details the specific relief, legal basis, covered taxpayers, beginning and ending dates, and the date postponed taxes must be paid. The IRS is also directed to announce the penalty relief publicly and to assess how it will allocate fuel-tank inspection resources during the relief period.
The Secretaries of Agriculture and Transportation are tasked with supporting implementation through coordination with agricultural stakeholders, state governments, industry groups, and labor organizations. The White House is engaging states to encourage corresponding policies, but any state-level relief would follow separate rules and is not guaranteed by the federal order.
Readers should verify the exact scope of relief once Treasury and IRS guidance is released, including who qualifies, any exceptions, and precise deadlines. The announcement does not create enforceable rights against the government, and implementation remains subject to applicable law and available appropriations.
Announcement covered: Oct 5, 2026.
General information only, not individual tax, legal, or financial advice. Rules, deadlines, and eligibility depend on your circumstances. Check current official guidance or consult a qualified professional.
Request a correction →