- The exemption under Act 2026-595 runs from September 1, 2026, through August 31, 2029, and covers only designated commercial agricultural operations.
- Qualifying businesses must obtain and present a Form STE-3 Utility Tax Certificate of Exemption to their utility provider; mixed-use accounts require separate metering.
- The exemption does not apply to natural gas or electricity used in industrial hemp or cannabis production.
Announcement and Effective Period
On September 24, 2026, the Alabama Department of Revenue issued a notice detailing new utility tax exemptions authorized by Act 2026-595.
The exemptions became effective on September 1, 2026, and will remain in force until August 31, 2029. This three-year window applies specifically to the furnishing of natural gas or electricity when used as fuel or energy in certain commercial agricultural activities.
Qualifying Uses and Exclusions
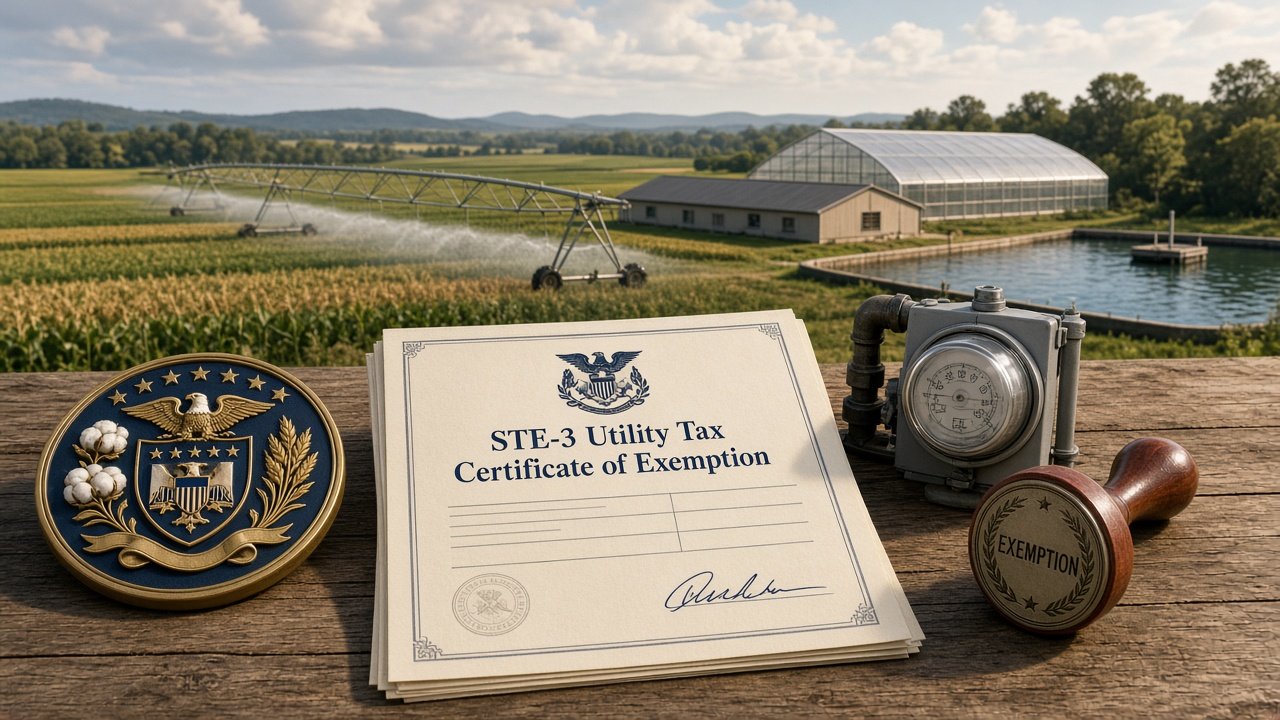
According to the Alabama Department of Revenue, the Utility Gross Receipts Tax no longer applies to natural gas or electricity consumed in commercial aquaculture aeration systems, commercial greenhouses, pivot irrigation systems, and poultry houses.
The notice explicitly states that this exclusion does not extend to the furnishing of natural gas or electricity used or consumed as fuel or energy in the production of industrial hemp or cannabis.
Only the qualifying utility usage itself is exempt; the exemption is limited to the specific operations identified in the act.
How to Claim the Exemption
To take advantage of the exemption, businesses must first obtain a Form STE-3 Utility Tax Certificate of Exemption from the Alabama Department of Revenue.
Once obtained, the certificate should be provided to the electric or natural gas utility provider. The Department provides both a printable application (ST-EX-A3) and an electronic option through the myalabamataxes.alabama.gov portal by registering a business or obtaining a new tax account number.
If a single utility account serves both exempt and non-exempt uses, the Alabama Department of Revenue requires separate metering to properly apply the exemption.
Questions for Affected Operations
Readers operating commercial aquaculture, greenhouses, irrigation systems or poultry facilities should verify whether their specific energy consumption patterns meet the act’s definitions and confirm proper documentation procedures with their utility providers.
The notice directs any questions about the exemption to the Sales and Use Tax Division of the Alabama Department of Revenue.
Republic Tax Relief notes that this new exemption addresses only utility taxes on qualifying agricultural energy use and does not resolve any separate existing tax debt issues; businesses with prior IRS or Alabama tax liabilities may contact the firm for a free, no-obligation initial consultation to evaluate private tax-resolution options, suitability, scope, fees and availability of help communicating with taxing authorities.
Announcement covered: Sep 24, 2026.
General information only, not individual tax, legal, or financial advice. Rules, deadlines, and eligibility depend on your circumstances. Check current official guidance or consult a qualified professional.
Request a correction →