- Wholesalers and registered retailers must obtain a no-fee Vapor Products Tax License from ALDOR to sell consumable vapor products legally.
- The tax is due by the 20th of each month for the prior month's sales, with a 4.75% timely-filing discount available only on full payments.
- Affected businesses should verify registration, reporting on the WRAP form, and potential penalties for noncompliance directly with the Alabama Department of Revenue.
Overview of the New Tax
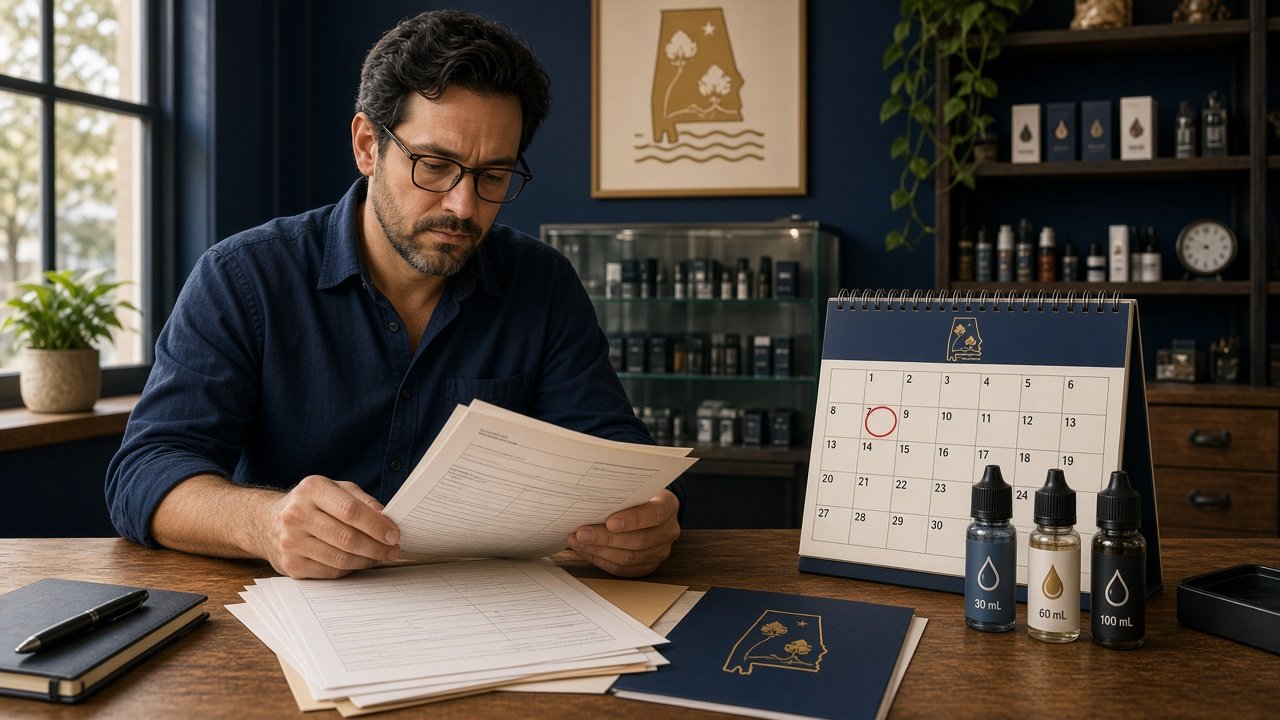
The Alabama Department of Revenue announced that a new state excise tax on consumable vapor products took effect on October 1, 2026, following the passage of Act 2025-377. This tax applies at a rate of 10 cents per milliliter on all such products sold at wholesale or imported into the state for use, consumption, or retail sale.
The announcement, dated September 28, 2026, clarifies that the responsibility for collecting and remitting this tax falls on wholesalers and registered retailers. Small business owners operating in this sector should review whether their activities meet the definitions under the act, as the tax does not automatically apply to every operation.
This change represents an additional compliance layer for businesses handling vapor products, separate from any existing sales or other excise taxes.
Registration Requirements for Businesses
Starting October 1, 2026, businesses can register for a Vapor Products Tax License at no cost through the My Alabama Taxes portal at myalabamataxes.alabama.gov. Once approved, the Alabama Department of Revenue mails a registration letter outlining reporting requirements, followed separately by the actual license.
Only businesses that sell consumable vapor products are subject to these rules. Those without the required license or who fail to apply the tax appropriately may face penalties, according to the department.
Small-business owners should confirm their specific role—whether wholesaler, importer, or retailer—before assuming obligations, as the rules target defined activities rather than all vape-related commerce.
Reporting, Payment, and Available Discount
The tax must be reported and paid by the 20th day of each month covering the preceding calendar month's activity. A 4.75 percent discount applies to returns and payments that are both filed and paid on time; however, the discount is disallowed if the full amount is not received by the due date.
In addition, consumable vapor products must be included on the Sales for Resale Report, known as the WRAP report. This integration means businesses already filing WRAP will need to incorporate the new tax details into their existing process.
Owners should calculate volumes carefully in milliliters to determine exact liability and monitor payment timing to preserve eligibility for the discount.
Questions Business Owners Should Verify
Small businesses affected by this tax should contact the Alabama Department of Revenue to confirm registration status, exact product classifications, and how the tax interacts with their current recordkeeping. The department's notice provides additional details on the registration process.
Republic Tax Relief notes that business owners with existing IRS or state tax debt questions unrelated to this vapor products tax may benefit from speaking with a qualified tax professional; the firm offers a free, no-obligation initial consultation to evaluate suitability, scope, fees, and options for communicating with taxing authorities.
For official guidance, visit the Alabama Department of Revenue website at revenue.alabama.gov or reach the Tax Policy and Governmental Affairs Division.
Announcement covered: Sep 28, 2026.
General information only, not individual tax, legal, or financial advice. Rules, deadlines, and eligibility depend on your circumstances. Check current official guidance or consult a qualified professional.
Request a correction →