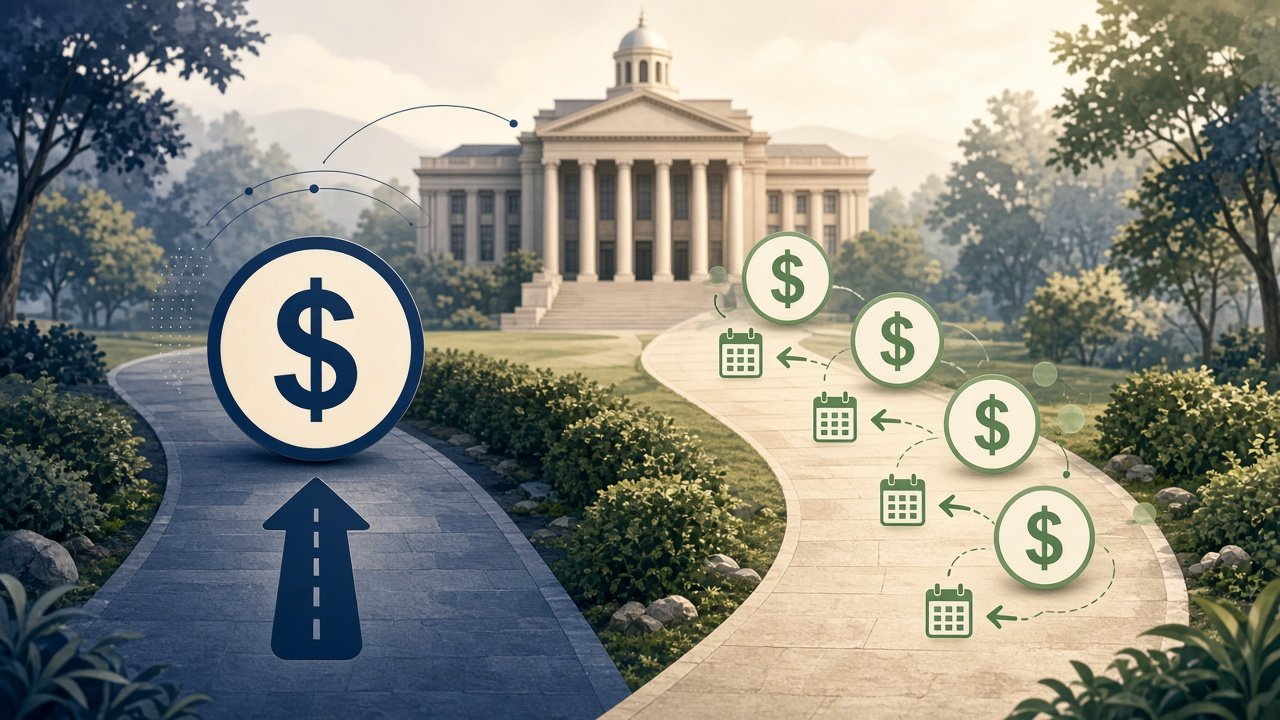
- Lump-sum offers require an upfront payment of 20 percent of the offered amount with the application.
- Periodic offers require an initial payment plus continued payments throughout the IRS review period.
- Low-income individuals may submit without the application fee or required payments during review.
- Payments made with any application are applied to the tax debt and are not refunded if the offer is returned.
For background on this issue, read our Offers in compromise guide.
Initial Payment Requirements
When submitting an Offer in Compromise application, the first payment depends on the chosen payment structure. For a lump-sum offer, the taxpayer must send 20 percent of the total proposed offer amount along with the application.
For a periodic payment offer, the taxpayer submits an initial payment equal to the first proposed installment when applying. The IRS applies these payments to the outstanding tax debt whether or not the offer is ultimately accepted.
Payments During IRS Review
Payment obligations continue to differ while the IRS evaluates the offer. A lump-sum offer requires no further payments during the review process. If accepted, the remaining balance must be paid in five or fewer installments.
A periodic payment offer requires the taxpayer to continue making the proposed periodic payments for the full offer amount throughout the IRS review. These payments must be maintained even though most collection activities are suspended during consideration.
The IRS guidance states that all required OIC payments must continue during the application process. Failure to make them can affect the status of the offer.
Low-Income Qualifications
Only individuals who meet low-income qualifications are exempt from the application fee, the initial payment, and any periodic payments while the IRS reviews the offer. Businesses do not qualify for this exception.
If the IRS determines an applicant is ineligible after submission, it returns the application and the application fee. Any payments already submitted are applied to the tax debt.
Considering Your Tax Debt Options
An Offer in Compromise may allow settlement of a tax debt for less than the full amount owed when full payment would create financial hardship or is not possible based on income, expenses, and asset equity. Before pursuing an OIC, the IRS recommends exploring other payment options.
Republic Tax Relief provides private tax-resolution services for individuals and businesses facing IRS or state tax issues. The firm offers a free, no-obligation initial consultation to discuss suitability of available options for those with existing tax-debt questions separate from OIC eligibility.
Applicants should use the IRS Offer in Compromise Pre-Qualifier Tool to check basic eligibility before submitting Form 656 and the required payment. All tax returns must be filed, estimated payments current where applicable, and the taxpayer must not be in an open bankruptcy.
IRS guidance checked .
General information only, not individual tax, legal, or financial advice. Rules, deadlines, and eligibility depend on your circumstances. Check current official guidance or consult a qualified professional.
Request a correction →