- The comment submission deadline for the Qualified Opportunity Zone proposed regulations has been corrected to October 26, 2026.
- The change is a narrow correction to the original September 11, 2026 Federal Register notice and does not alter the substance of the proposed rules.
- Interested parties should submit written comments by the new deadline to ensure they are considered.
Background on the Proposed Regulations
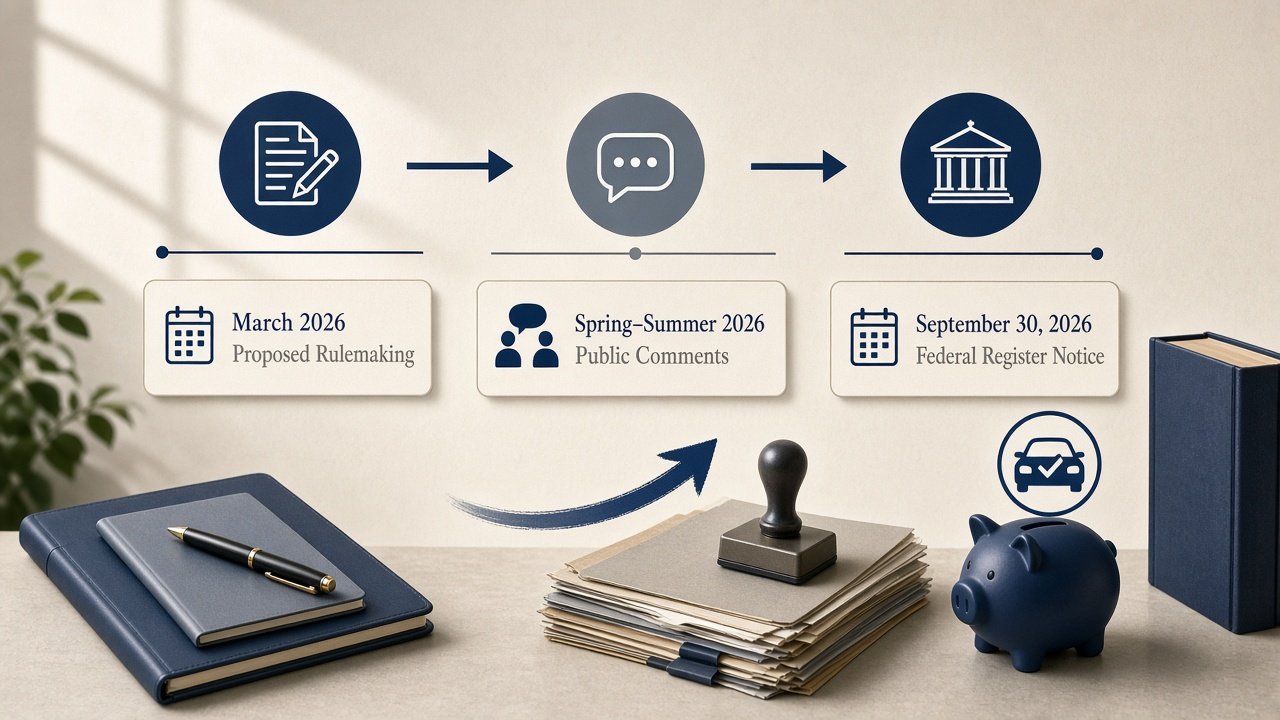
On September 11, 2026, the Internal Revenue Service published proposed rules in the Federal Register concerning information reporting for Qualified Opportunity Zones and updated procedures for Qualified Opportunity Fund certification and decertification.
The original notice included a public comment period that was set to close on October 16, 2026. This proposal builds on existing Qualified Opportunity Zone provisions that encourage investment in designated low-income census tracts through tax incentives.
The context of these proposed changes reflects ongoing efforts to improve transparency and compliance within the Opportunity Zone program, which has been in place for several years.
Details of the Technical Correction
The IRS published a correction notice on September 28, 2026, adjusting the comment deadline. The new deadline for submitting comments on the proposed regulations is now October 26, 2026.
This is strictly a date correction and does not modify any other aspects of the proposed rule, such as the reporting requirements or the certification and decertification processes for Qualified Opportunity Funds.
The correction was necessary to address an error in the original document that appeared in the September 11 issue.
Who Should Pay Attention
Investors, fund managers, tax professionals, and other stakeholders involved with Qualified Opportunity Funds or investments in Qualified Opportunity Zones are affected by this timeline adjustment.
Those planning to review the proposed information reporting rules and certification updates now have additional time until October 26, 2026 to prepare and submit comments.
Republic Tax Relief notes that while this announcement focuses on program reporting and certification rather than existing tax debt, individuals or businesses with separate IRS tax issues may wish to contact the firm for a free, no-obligation initial consultation to evaluate private tax-resolution options and discuss suitability, scope, fees, and availability of assistance communicating with the IRS.
What Readers Should Verify
Stakeholders should confirm the exact new comment deadline and review the full proposed rule text to understand the scope of the information reporting and certification changes.
Comments must be submitted in writing by October 26, 2026, following the instructions outlined in the original notice.
The correction does not extend any other deadlines or alter eligibility for Opportunity Zone benefits.
Announcement covered: Sep 28, 2026.
General information only, not individual tax, legal, or financial advice. Rules, deadlines, and eligibility depend on your circumstances. Check current official guidance or consult a qualified professional.
Request a correction →