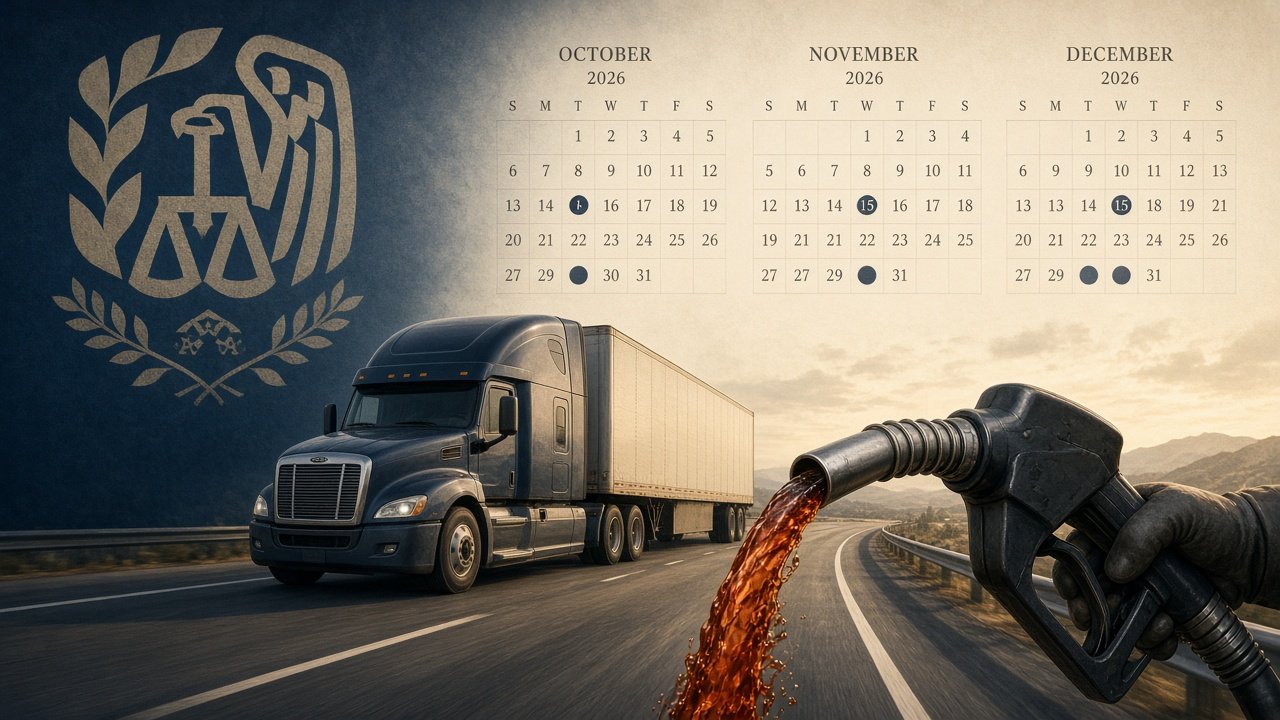
- No federal penalties apply to dyed diesel sold for or used on highways from Oct. 1 through Dec. 31, 2026 nationwide.
- Recordkeeping, semimonthly deposits, and federal fuel inspections are suspended during the relief period.
- This federal relief does not affect state excise taxes; check with your state agency for applicable rules.
For background on this issue, read our Penalty relief guide.
What the IRS Announced
On October 14, 2026, the Internal Revenue Service stated it will not impose penalties when dyed diesel fuel is sold for highway use or used to power vehicles on highways. The relief responds to President Trump’s Executive Order issued October 5, 2026, titled Emergency Tax Relief on Diesel Fuel.
The change is retroactive to October 1, 2026 and ends December 31, 2026. It covers any person who sells dyed diesel fuel for highway use or who uses it that way. Normally such actions would trigger federal excise tax liability and penalties.
Republic Tax Relief notes that readers with separate existing IRS tax debt questions unrelated to this diesel-fuel relief may wish to contact the firm for a free, no-obligation initial consultation about private tax-resolution services and suitability for their situation.
Practical Effects During the Relief Period
The IRS will suspend ordinary collection and enforcement procedures. All Fuel Compliance Officers are being reassigned, and no federal inspections of on-road dyed fuel usage will take place.
Taxpayers do not need to maintain records to substantiate eligibility for this relief. Sellers and distributors have no obligation to investigate or document the ultimate end-use of dyed fuel sold in this window. Penalties for failure to make semimonthly deposits or maintain adequate records are also waived for the covered activity.
Key Items That Require Verification
This announcement addresses only federal excise tax penalties under the specified code sections. It does not postpone or forgive the underlying tax itself. The IRS expects to issue further guidance on postponement of payment under 26 U.S.C. 7508A and possible elimination of deferred amounts.
Forthcoming guidance will also clarify how the relief affects Form 720 Quarterly Federal Excise Tax Return and any other relevant forms. Taxpayers should monitor IRS updates before filing returns that cover the relief period.
The relief applies solely to federal tax purposes. It has no effect on state fuel taxes or state penalties. Many states have issued similar relief, but coverage varies. Each taxpayer should consult their state tax agency for current rules on dyed diesel used on highways.
What to Do If You Receive a Penalty Notice
If a taxpayer receives a penalty notice that appears to conflict with this relief, they should follow the instructions printed on the notice or contact the IRS directly for assistance. The announcement does not alter standard procedures for disputing notices.
Announcement covered: Oct 14, 2026.
General information only, not individual tax, legal, or financial advice. Rules, deadlines, and eligibility depend on your circumstances. Check current official guidance or consult a qualified professional.
Request a correction →